Coal Liquefication Price Trend Analysis 2026: Supply Demand Analysis, Historical Prices, Price Drivers, Latest News & Market Insights

Written ByVikas Jha

Procurement Resource Database

Laptop screen

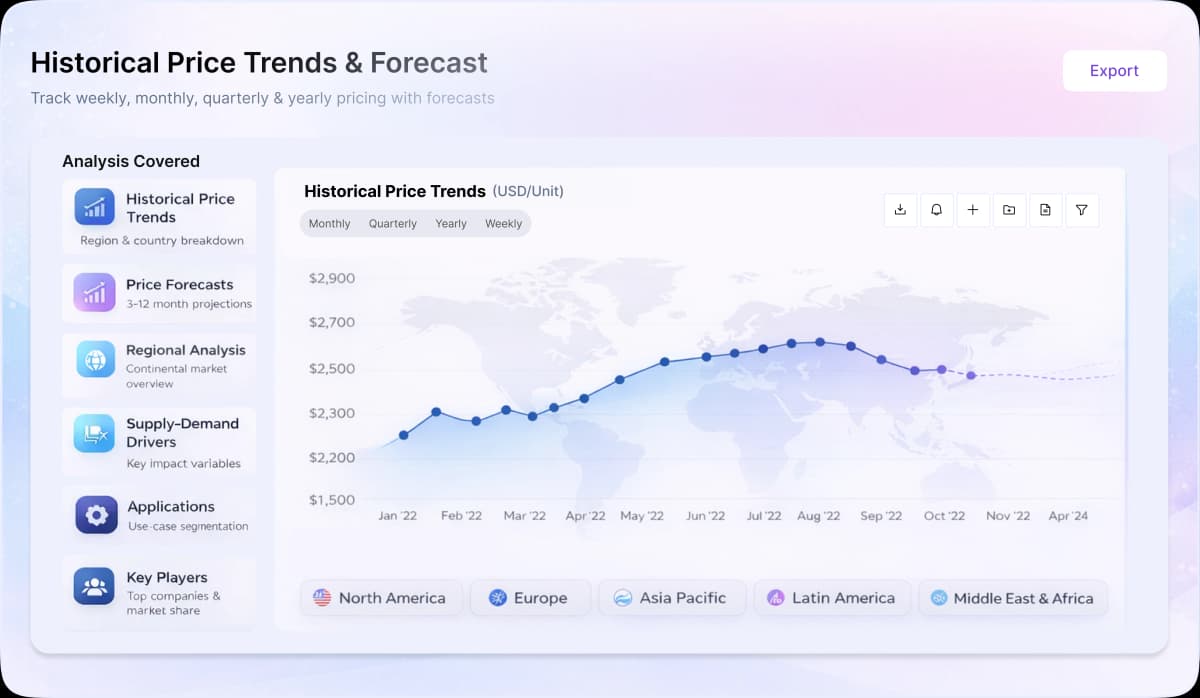
Turn price intelligence into action with the Procurement Resource Database. Log in or subscribe to unlock live price trends, historical charts, supplier databases, cost curves, and analyst-backed insights across chemicals, agriculture, energy, packaging, and more. Use these tools to benchmark your contracts, plan budgets with confidence, and stay ahead of market moves on every product you buy.

0

+

Products

0

+

Regions

0

+

Subscriptions

In the third quarter of 2025, coal liquefaction prices remained largely subdued due to weaker coal prices globally and reduced demand for coal-based fuels. In India, where coal is still widely used, imported LNG continued to struggle to replace coal, but even there, coal liquefaction remained a small, less competitive option.

With gas and renewable energy expanding their roles, the economic case for coal-to-liquid (CTL) projects weakened further. India’s underused gas infrastructure and low uptake of LNG meant no major shift toward CTL for power or industry, keeping demand and pricing soft.

Meanwhile, in China, coal prices declined significantly during the quarter due to stable domestic production and growing renewable capacity. This added further pressure on coal liquefaction economics, as the cost advantage of CTL narrowed against other fuels.

Despite short-term spikes during peak summer, overall coal demand was met easily through local production and imports. As a result, CTL producers had little pricing power and faced challenges staying competitive, especially with increasing availability of cleaner energy options.

About Coal Liquefication

Coal is transformed into liquid hydrocarbons, such as fuel and petrochemicals, through the process of coal liquefaction. The "indirect route" and the "direct route" are the two most popular methods for completing this task, though there are other methods as well. This conversion is advantageous for nations with abundant coal resources (like the US and China), as it can lessen reliance on imported liquid fuels. It also has the potential to generate hydrogen economically.

Coal Liquefication Product Detail

Industrial Uses

Production of gasoline, Production of hydrogen

Supplier Database

Chevron Corporation, Pall Corporation, Shenhua Group, Yankuang Company, Jincheng Anthracite Mining Group

Regional Coverage

Asia Pacific

China, India, Indonesia, Pakistan, Bangladesh, Japan, Philippines, Vietnam, Iran, Thailand, South Korea, Iraq, Saudi Arabia, Malaysia, Nepal, Taiwan, Sri Lanka, UAE, Israel, Hongkong, Singapore, Oman, Kuwait, Qatar, Australia, and New Zealand

Europe

Germany, France, United Kingdom, Italy,Spain, Russia, Turkey, Netherlands, Poland, Sweden, Belgium, Austria, Ireland Switzerland, Norway, Denmark, Romania, Finland, Czech Republic, Portugal and Greece

North America

United States and Canada

Latin America

Brazil, Mexico, Argentina, Columbia, Chile, Ecuador, and Peru

Africa

South Africa, Nigeria, Egypt, Algeria, Morocco

CurrencyUS$ (Data can also be provided in local currency)

Supplier Database AvailabilityYes

Customization ScopeThe report can be customized as per the requirements of the customer

Post-Sale Analyst Support360-degree analyst support after report delivery

Note: Our supplier search experts can assist your procurement teams in compiling and validating a list of suppliers indicating they have products, services, and capabilities that meet your company's needs.

Coal Liquefication Production Processes

  • Coal Liquefication Production from Direct Liquefaction; from Indirect Liquefaction

In this procedure, iron-based catalyst and recycled solvent are present while coal is exposed to hydrogen at 450°C and high pressure for one hour. As a result, the solid to liquid transformation of coal's hydrocarbon structure occurs. In order to produce consumable oil, it goes through extensive upgrading.

Frequently Asked Questions

The coal liquefaction outlook remains tied to winter heating-season demand and structural constraints on global coal supply. Cold weather and strong LNG exports typically drive US utilities toward coal, depleting inventories and lifting prices, while Chinese supply tightens during production inspections and seasonal restocking. European geopolitical tensions can make coal a more attractive alternative to gas, reinforcing firmness. Prices would ease if coal production recovers or LNG supply expands, but strategic stockpiling and recurring supply tightness tend to keep the outlook firm.
Coal liquefaction prices respond to winter heating demand, natural gas price movements, and regional supply disruptions. In the United States, cold weather and strong LNG exports push utilities toward coal, drawing down inventories. In China, heavy rainfall and production inspections periodically tighten supply, while seasonal restocking boosts demand, though slower steel production can temper gains. In Europe, geopolitical tensions and LNG supply concerns make coal more attractive, with temporary shortages producing price spikes. Strategic stockpiling by industrial consumers adds further upward pressure during tight periods.
Coal liquefaction prices are driven by coal feedstock availability, natural gas input costs, and seasonal winter demand across major markets. In the United States, surging natural gas prices push utilities toward coal, lifting liquefaction product demand as inventories decline. In China, production inspections and supply restrictions periodically tighten feedstock availability. In Europe, geopolitical tensions and LNG supply concerns support coal demand. The cost structure is anchored in coal procurement, energy inputs for processing, and logistics, with winter demand and supply constraints shaping near-term price firmness.
Coal liquefaction costs are shaped by coal feedstock pricing. In China, heavy rainfall, production inspections, and supply restrictions periodically tighten coal availability, pushing feedstock costs higher. In the US, surging natural gas prices from cold weather and strong LNG exports can drain coal inventories, pushing fuel costs upward. European prices are supported by stable power and industrial demand, with geopolitical tensions and LNG considerations making coal more attractive. Transport and logistics costs generally stay stable, while strategic stockpiling by industrial consumers ahead of winter sustains demand-side pressure.
Petrochemical, chemical, power generation and fuel refining sectors are most exposed, relying on liquefied coal as feedstock for plastics, rubber, coatings and fuel products. Surging winter fuel demand and declining US coal inventories typically push utilities toward coal, tightening feedstock supply and raising production costs. Industrial stockpiling amplifies this pressure, while slower steel output in China can offer only partial offset. Geopolitical tensions and LNG supply concerns further sustain coal's attractiveness, keeping liquefaction costs firm across these sectors during winter demand peaks.
Coal liquefaction prices move differently across key regions depending on local supply constraints and energy-market linkages. In the United States, cold winter weather and strong LNG exports push natural gas prices higher, pulling coal demand up and tightening domestic supply. China tends to see sharper swings from production inspections and heavy rainfall restricting output, tempered by steel-sector demand. Europe generally holds steadier, with import flows and geopolitical LNG concerns supporting demand without sharp spikes. The regional gap reflects differing supply constraints, seasonal demand, and energy-market linkages.
Coal liquefaction prices are influenced by crude oil prices through multiple channels. Higher crude prices raise fuel, hydrogen, and utility costs while making coal liquefaction more economically attractive, boosting demand and supporting higher prices. Crude-driven energy costs and fuel logistics add to production expenses during periods of tight coal supply and strong winter demand. Crude oil price shifts are typically transmitted to coal liquefaction feedstock costs over roughly one to two months, reflecting contract cycles and inventory adjustments.
Procurement Resource assesses coal liquefaction price trends through a structured, data-driven methodology. Primary engagement with producers, suppliers and traders is combined with secondary market data, continuous monitoring of feedstock and input costs, trade-flow and inventory tracking, and exchange or spot benchmarks. All inputs are validated and translated into a transparent price assessment and outlook. The detailed methodology is available on the Procurement Resource website.

Our Price Analysis Methodology

About the Author

Vikas Jha profile photo

Vikas Jha

Vice President - Sales and Operations

Driving growth and operational excellence at Procurement Resource by partnering with global enterprises on procurement consulting and client solutions, with expertise in scaling research operations and delivering actionable commodity intelligence.

Schedule Demo

Schedule A Demo

Experience how Procurement Resource transforms raw material price data into clear, decision ready intelligence. Optimise your performance with reliable, expert market data and analysis. Schedule your demo today to experience a live walk-through where our experts will showcase interactive price charts, forecasted prices, and insights driving the prices for your key commodities, tailored to your workflows. Contact us now!

Our Team will be happy to assist you

We are just a text away

+1

Still Need Help?

Europe & Africa

+44 7573 171117

Sales@procurementresource.com

USA & Canada

+1 307 363 1045

Sales@procurementresource.com

APAC

+91 8850629517

Sales@procurementresource.com

Unlock full access to Procurement Resource's price databases, interactive charts, and short-term forecasts for thousands of commodities. Elevate your sourcing decisions by comparing prices across regions, downloading historical data, and layering in analyst-backed insights, all with our flexible plans that scale as your portfolio grows.

Still have any Questions

Contact Us
Mastercard
Wire
VISA
Stripe

Why Procurement Database

Commodity Market Intelligence

Commodity Market Intelligence

Track prices, market movements, supply-demand dynamics, and industry developments across hundreds of commodities through a centralized intelligence platform built for informed procurement decisions.

Price Forecasts & Market Outlooks

Price Forecasts & Market Outlooks

Understand market fluctuations using analyst-backed forecasts, historical pricing patterns, and evolving industry trends to strengthen sourcing strategies and budget planning.

Cost & Procurement Optimization

Cost & Procurement Optimization

Leverage cost models, pricing benchmarks, and procurement insights to evaluate purchasing opportunities, improve negotiations, and enhance operational efficiency.

Global & Regional Market Insights

Global & Regional Market Insights

Access region-specific price trends, trade activities, capacity changes, and supply chain developments influencing commodity markets worldwide.

1/4