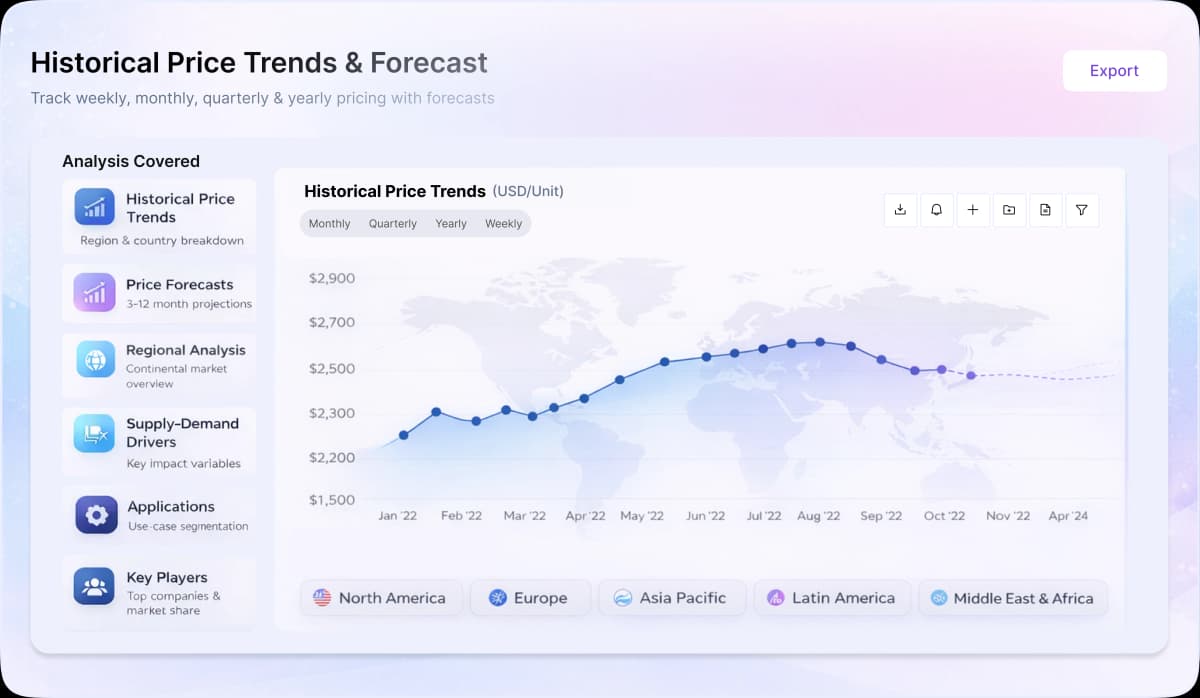
- Crude coconut oil prices stayed stable to soft globally in Q1’26 as better coconut availability and recovering export volumes eased supply tightness after the strong 2025 rally.
- Copra availability improved in Asia, but millgate copra costs remained above early-2025 levels, keeping raw material pressure embedded in the market.
- Downstream refined coconut oil demand from food, bakery, confectionery, cosmetics, personal care, and wellness sectors stayed steady but price sensitive.
Asia
Crude coconut oil prices in Asia softened during Q1’26 as improved harvest conditions and better coconut availability supported crushing activity. The Philippines remained the key supply driver, with production forecast to recover to nearly 1.60 million metric tons in 2026 from 1.36 million metric tons in 2025. Indonesia’s output is also expected to rise to around 827,000 metric tons from 768,000 metric tons in 2025, improving regional supply availability. However, Philippine coconut oil export revenues declined 12.9% year-on-year to USD 661.06 million during Q1’26, while February exports fell 5.8%, showing uneven trade recovery. Indonesia supported a wider vegetable oil trade, with HS 15 exports reaching 3.06 billion kg in February 2026. Demand from refined coconut oil producers stayed need-based, limiting upward price pressure.
Europe
Crude coconut oil prices in Europe remained stable to firm in Q1’26 due to import dependency and firm landed costs. EU imports are forecast to rise to about 629,000 metric tons in 2026 from 594,000 metric tons in 2025, supported by steady demand from refined coconut oil, bakery, cosmetics, and oleochemical sectors. However, freight and marine insurance costs remained high, while buyers preferred early but controlled procurement to avoid supply gaps. EUDR-compliant coconut oil continued to attract a premium among European buyers.
North America
Crude coconut oil prices in North America stayed stable to slightly soft in Q1’26. U.S. imports are expected to recover to around 410,000 metric tons in 2026 from 380,000 metric tons in 2025. Adequate inventories and regular Southeast Asian shipments prevented supply tightness, while refined coconut oil demand from processed food, vegan products, supplements, and personal care stayed steady.