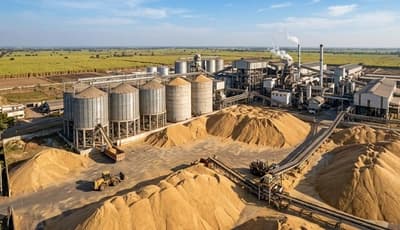
- Raw sugar markets remained broadly weak during H1 2026 as abundant Brazilian supply and improving Asian output outweighed occasional weather and policy concerns.
- Higher cane availability increased crushing potential, although stronger ethanol allocation in Brazil temporarily restricted the volume directed toward sugar production.
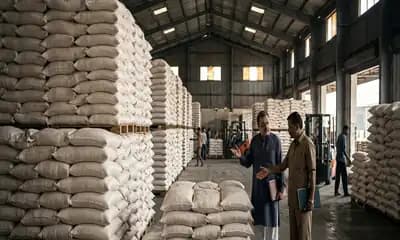
- Import demand remained steady across major consuming markets, but buyers stayed cautious as ample export availability reduced the need for aggressive stockbuilding.
During H1 2026, raw sugar prices remained generally under pressure, with short-lived recoveries failing to develop into a sustained rally. Brazil was the main bearish influence as strong cane crushing and rising Center-South sugar output increased export availability, while ethanol diversion prevented an even sharper decline. Brazilian raw sugar exports were estimated at 29.94 million MT in MY2025/26, maintaining substantial supply to global buyers. Asian markets also faced improving availability as Thailand benefited from a stronger cane crop and higher extraction, with sugar production expected to rise 10% year on year. India initially added potential export supply, but weak export economics encouraged mills to prioritize domestic sales before tighter export controls emerged late in H1. Indonesia remained a major demand centre, with raw sugar imports estimated at 3.8 million MT, largely sourced from Brazil, Thailand and Australia. These trade flows kept Asian buyers well supplied despite periodic Black Sea-style logistics and freight concerns elsewhere in commodities.