- Global viscose staple fibre markets remained firm in Q2’26 as low inventories and disciplined producer offers supported prices despite uneven textile demand.
- Feedstock conditions were broadly balanced, with dissolving pulp availability limiting cost pressure while cellulose-chain inputs provided selective support.
- Downstream demand remained cautious, with textile buyers focused on immediate needs rather than large inventory building during the quarter.
Asia
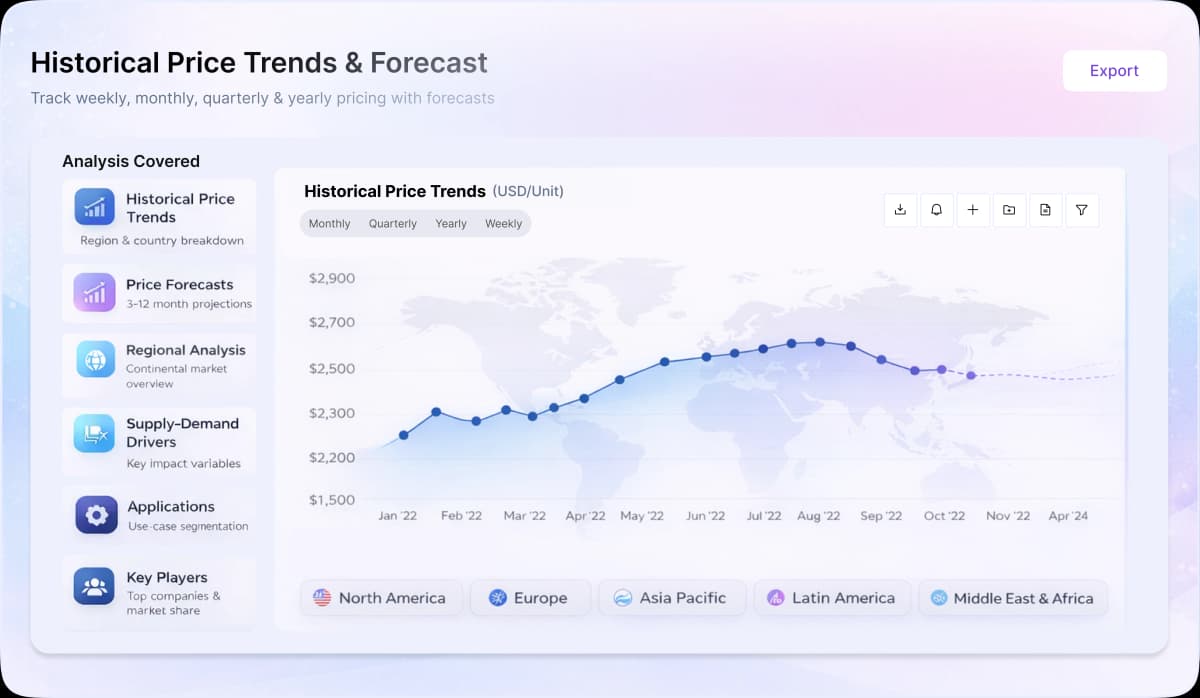
Viscose Staple Fibre prices in China increased to ~USD 1,948.31/MT in April and ~USD 2,084.00/MT in June, showing a ~7.0% increase. Meanwhile, in India, prices increased to ~USD 1,998.30/MT in April and ~USD 2,172.00/MT in June, showing a ~8.7% increase. Asian markets strengthened during April and May as low VSF inventories, firm fibre prices and producer discipline supported higher offers. Dissolving pulp conditions remained relatively stable, shifting the main price support toward supply management rather than raw-material inflation. China’s pulp imports reached 3.218 million tonnes in April, indicating comfortable broader cellulose availability. Textile buyers remained cautious, with spinning and weaving mills mainly purchasing for immediate production requirements, limiting further price gains by June.
Europe
European VSF conditions remained mixed as higher logistics and production costs supported pricing, while weak textile demand restricted stronger increases. Fibre producers faced elevated energy and operating expenses, but downstream purchasing remained cautious. European retail activity weakened, with non-food retail declining, affecting apparel-related demand. Broader pulp availability remained comfortable, reducing the likelihood of severe feedstock shortages. The market therefore remained supported by cost factors but limited by slower textile-chain recovery.
North America
North American VSF prices increased to ~USD 2,035.30/MT in April and ~USD 2,239.00/MT in June, showing a ~10% increase. Imported fibre costs received support from higher freight rates and supply-chain expenses, while manufacturing activity provided some demand support. However, pulp availability remained mixed, with adequate softwood supply limiting raw-material pressure. Inventory building in manufacturing supported procurement activity, but final textile demand remained uneven.
Analyst Insight
According to Procurement Resource, in the near-term, VSF prices are expected to remain stable to firm as producers maintain supply discipline, while demand recovery across textile markets will determine further movement.