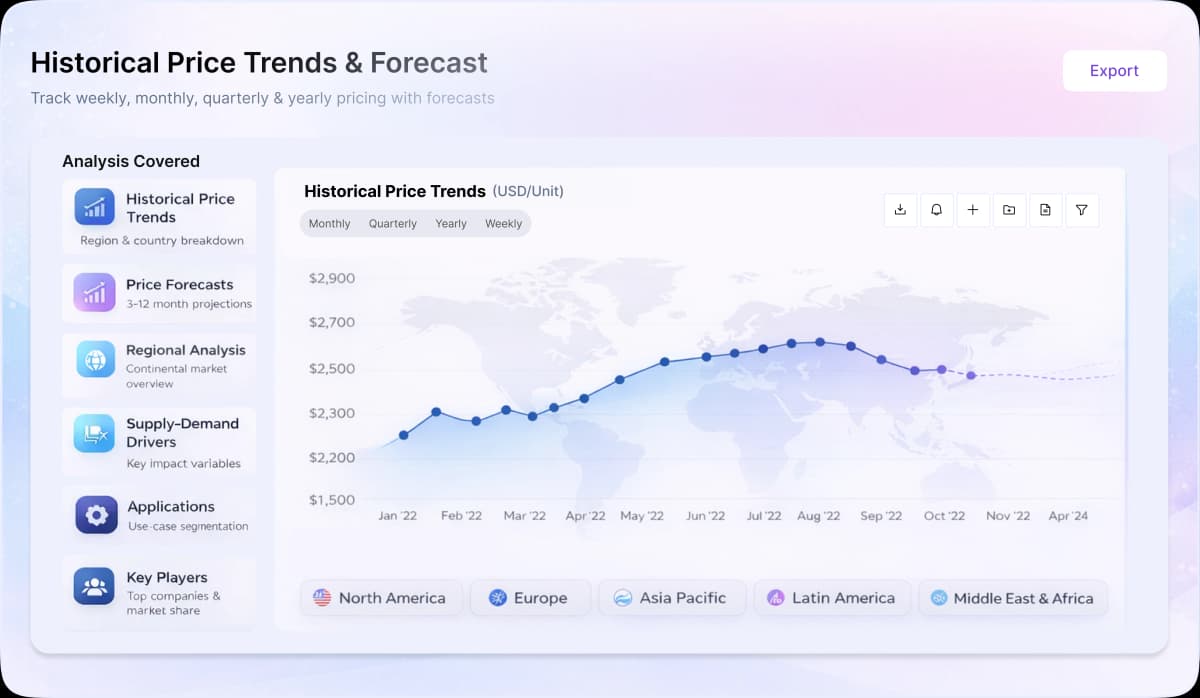
- Global caprolactam prices declined in Q2’26 as lower feedstock costs, sufficient supply and weak nylon demand pressured markets.
- Feedstock costs softened due to lower benzene, cyclohexanone and sulfur prices, reducing production cost support.
- Downstream demand remained uneven, with weak textile applications offset by support from automotive and engineering plastics.
Asia
Caprolactam prices in China declined to ~RMB 13.03/kg and ~RMB 12.29/kg during the first two months of Q2’26, showing a ~5.7% decrease. The market weakened as lower benzene, cyclohexanone and sulfur costs reduced the production-cost base, while domestic supply remained ample. Poor nylon-chip sales and rising inventories led several downstream polymerisation units to reduce output, increasing pressure on producers. Although some production cuts tightened spot availability later in the quarter, weak nylon margins and lower feedstock costs kept prices under pressure. Imports remained competitive, limiting domestic suppliers’ pricing ability, while export demand weakened due to stronger global competition. Downstream textile demand slowed seasonally, with spinning mills purchasing only immediate requirements.
Europe
Caprolactam markets in Europe remained weak during most of Q2’26 due to soft nylon demand and high operating expenses. Higher raw material costs, including sulfur and benzene, pressured producers initially, but weak downstream demand limited price recovery. Industrial activity remained subdued, reducing demand from consumer goods, appliances and construction-related nylon applications. Automotive demand provided partial support, with higher vehicle registrations supporting PA6 consumption in connectors, cable systems and lightweight components. Meanwhile, LEUNA-Polyamid, a significant European producer, filed for insolvency in June, affecting an integrated chain covering phenol, cyclohexanone, caprolactam and PA6 production.
North America
Caprolactam prices in the United States declined to ~USD 1,995.37/MT in April and ~USD 1,934.94/MT in May, showing a ~3.0% decrease. The market remained soft to stable as lower benzene and propylene costs reduced producer pricing support. Meanwhile, a modest recovery in the nylon market but continued pressure from subdued industrial demand and higher sulfur and natural gas costs. Automotive and construction-related applications provided some support, with improved vehicle production and residential construction activity. However, higher resin production compared with customer demand increased inventory pressure and limited stronger price movement.