Asia
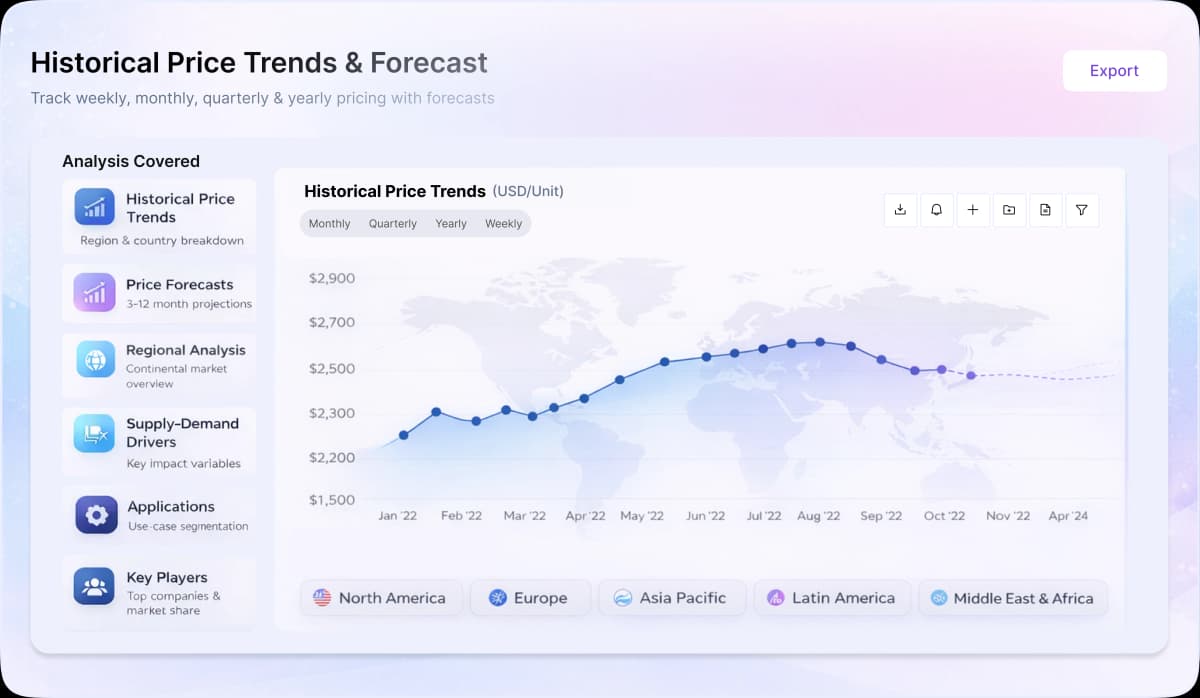
HDI prices in the Asia-Pacific region showed a mixed trend throughout the first half of 2025. In Q1, prices rose in January due to steady production and better feedstock supply. However, weak demand in automotive and construction, especially in China, led to a price drop in February.
After the Lunar New Year, stockpiles increased, keeping prices under pressure. In Q2, demand remained moderate in Southeast Asia, but China’s sluggish recovery and subdued property sector kept overall consumption low. Supply remained stable, but market sentiment stayed cautious due to inconsistent end-use sector performance.
Europe
In Europe, HDI prices were highly volatile in H1’25. Q1 began with a price surge due to limited raw material availability, geopolitical risks, and weather-related energy strain. But mid-quarter saw sharp declines as labor strikes, port congestion, and external trade tensions disrupted logistics.
In March, recovery began as production stabilized and demand from the automotive sector, especially EVs, picked up. In Q2, strong downstream demand from polyurethane applications in construction and automotive helped prices rebound further. However, supply chain issues, including port delays and rerouted shipments, kept supply tight and contributed to firm pricing.
North America
North American HDI prices showed a generally bullish trend in H1’25. Q1 faced weather-related production issues and shipping delays, but strong demand from automotive and construction industries supported pricing. In Q2, consistent offtakes and growing interest in electric vehicles continued to push demand. Although feedstock costs were relatively stable, freight and operational challenges added to the pricing pressure, keeping the market firm.