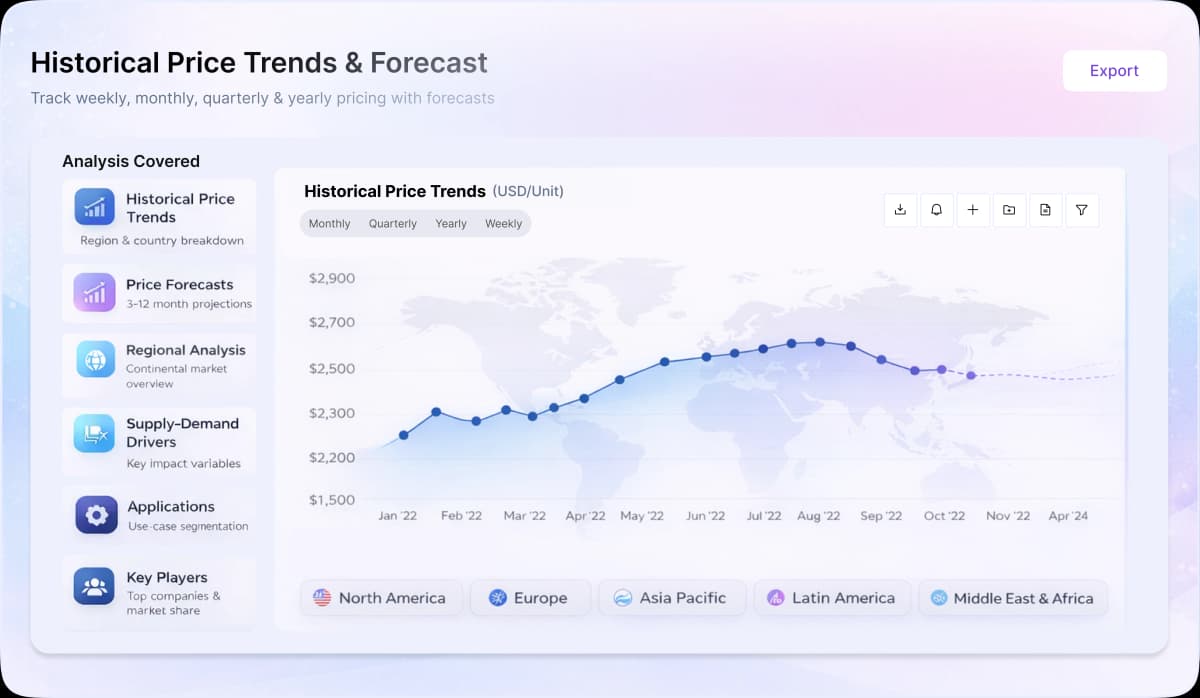
- Global iridium prices (Q1 2026): Iridium prices stayed firm in Q1 2026, supported by continued strength and tightness across the broader platinum group metals (PGM) market.
- Supply-side effect: Supply sentiment remained tight as Impala Platinum ruled out new greenfield projects despite the price rally, signaling limited future PGM output growth.
- Downstream impact: Demand sentiment was supported by improved outlook for combustion-engine-linked PGM usage after the EU softened its 2035 engine ban stance.
Iridium prices remained elevated through Q1 2026, largely tracking bullish sentiment in the wider platinum group metals complex. Market fundamentals were shaped by ongoing tight supply conditions from South Africa, a major global PGM-producing region, which had already driven precious metal prices sharply higher into early 2026. A key market development came from Impala Platinum, which stated that despite the ongoing rally, current price levels still do not justify new mining projects, with the producer instead focusing on extending the life of existing shafts to maintain output. This reinforced expectations of constrained future supply additions across PGMs, indirectly supporting iridium market firmness. On the demand side, sentiment improved after the European Union’s reversal on its 2035 combustion-engine ban, which supported expectations for longer-term autocatalyst-related PGM consumption, although structural pressure from electric vehicle adoption continued to limit stronger long-term demand confidence.