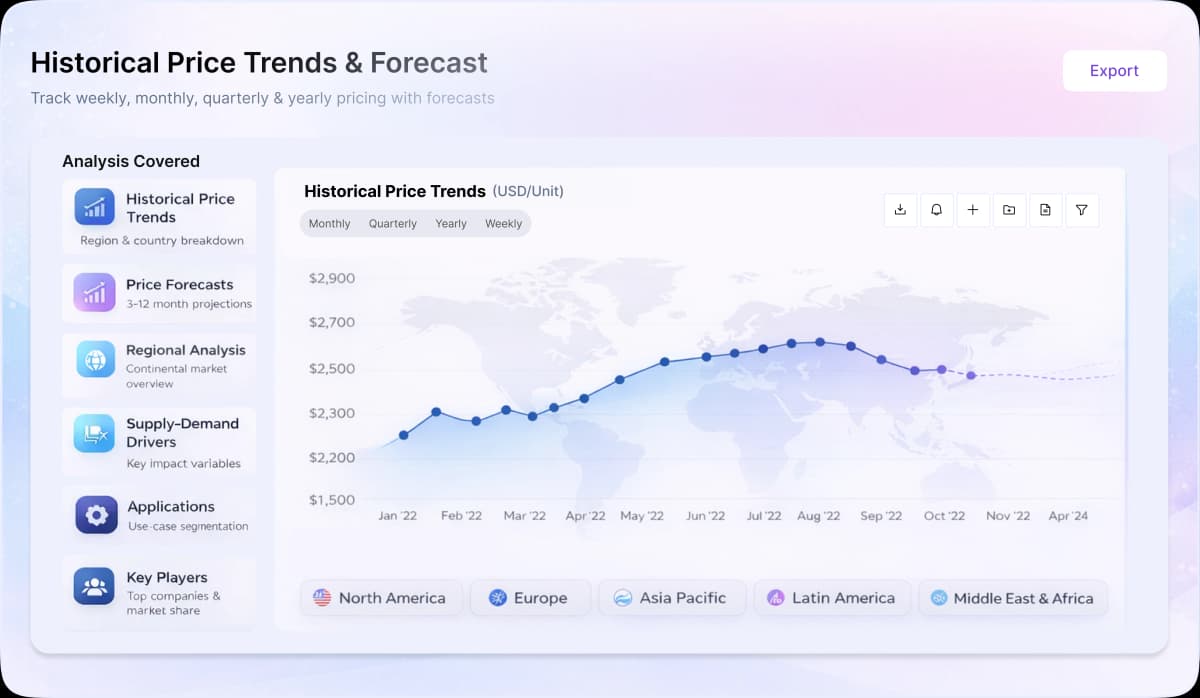
- Global met coke prices showed a weak-to-stable trend in Q1’26 as soft steel demand outweighed supply-side cost pressure, while late-quarter recovery was supported by tightening logistics and freight risks.
- Feedstock dynamics remained mixed, with coking coal supply stable but coke output constrained by structural shifts in steelmaking capacity.
- Downstream demand remained subdued as blast furnace utilization stayed low across regions, limiting coke consumption despite stable industrial activity.
Asia
Met coke prices in Asia followed a weak-to-stable trend in Q1’26, declining early due to high inventories and cautious procurement by steel mills, before stabilizing later in the quarter. Supply remained steady as coke production was supported by consistent coal availability, while downstream steel output stayed constrained. Freight and energy uncertainty increased toward March as geopolitical tensions raised transport costs, supporting marginal recovery. The market remained sensitive to steel production trends, with weak construction and manufacturing activity limiting demand for coke.
Europe
Met coke prices in Europe remained under pressure in Q1’26 due to weak steel sector fundamentals and reduced blast furnace activity. Demand remained limited as steel output stayed low, reflecting structural challenges in European steel production. Import dependence exposed the region to higher freight and energy costs following the Strait of Hormuz disruption, which carries about one-quarter of global seaborne oil trade, increasing logistics cost pressure. However, weak downstream demand prevented any significant upward movement, keeping the market subdued.
North America
Met coke prices in North America remained steady to slightly soft in Q1’26, supported by balanced domestic supply but constrained by moderate steel demand. U.S. coke production stood at around 10 million short tons in 2025, indicating reduced reliance on coke due to the shift toward electric arc furnace steelmaking. This structural shift limited both supply and demand, keeping the market stable. Higher fuel and freight costs added indirect pressure but did not significantly alter domestic supply conditions.