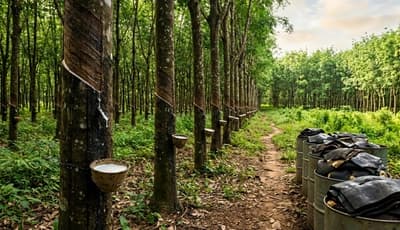
- Global natural rubber markets strengthened in Q2’26 as supply disruptions and firm consumption tightened availability before slight late-quarter correction.
- Feedstock conditions were affected by dry weather and delayed tapping, with April global production estimated at 772,000 MT against consumption of 1.235 million MT.
- Downstream demand remained supported by tire manufacturing, while rising inventories limited further price gains later in the quarter.
Asia
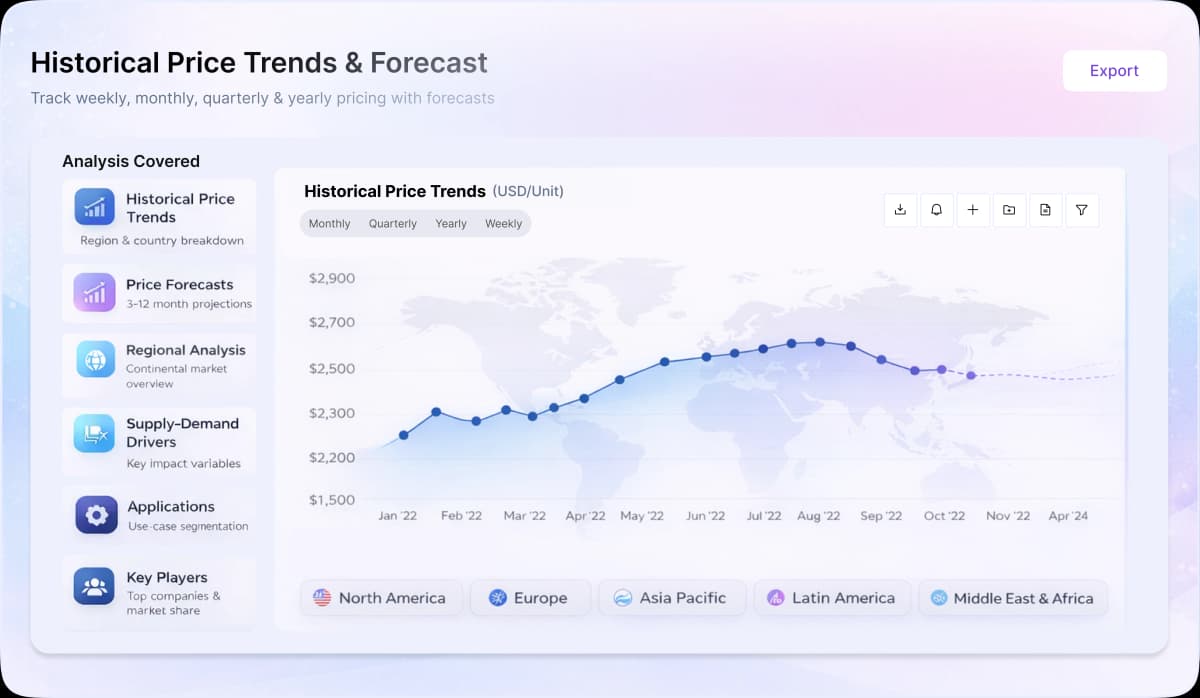
During the second quarter of 2026, natural Rubber prices in China were ~USD 2,455.68/MT in April and ~USD 2,601.00/MT in June, showing a ~5.9% increase. The market strengthened during April and May as drought and high temperatures delayed tapping activities in major producing regions. Raw latex availability tightened as Thailand, Vietnam and parts of China faced dry conditions. Global supply remained below consumption levels during April and May, supporting physical prices. Tire demand provided support, with Chinese tire plants maintaining relatively high operating rates during the quarter. However, rising finished tire inventories and requirement-based purchasing reduced buying intensity later. By June, increased arrivals from Southeast Asia and improving tapping conditions weakened the supply shortage premium.
Europe
Natural Rubber prices in Germany increased from ~USD 2,581.68/MT to ~USD 2,722.00/MT, showing a ~5.4% increase during Q2’26. European markets followed higher Asian import costs during the first part of Q2 due to supply constraints in major producing countries. Automotive demand provided some support, with EU new-car registrations increasing 4.0% year to date through May. Higher imported rubber costs affected tire manufacturers, but improved supply availability in late June reduced pressure as Asian markets corrected.
North America
Natural Rubber prices in the United States increased to ~USD 2,542.68/MT in April and ~USD 2,756.00/MT in June. Imported rubber costs strengthened due to Asian supply tightness, but downstream demand remained weaker than other regions. Truck tire original-equipment volumes declined, limiting buyers’ ability to absorb higher raw-material costs. Tire manufacturers faced delayed cost pass-through as raw-material movements gradually affected procurement decisions.