- Global refined soybean oil markets remained firm in Q2’26 initially but faced pressure later as vegetable-oil supply improved and inventories increased.
- Feedstock conditions improved as China’s MY 2026/27 soybean imports at 114.0 million metric tons (as projected by USDA), supporting larger crushing availability.
- Downstream demand remained balanced, with edible-oil consumption supported but higher inventories reducing buyer urgency in key markets.
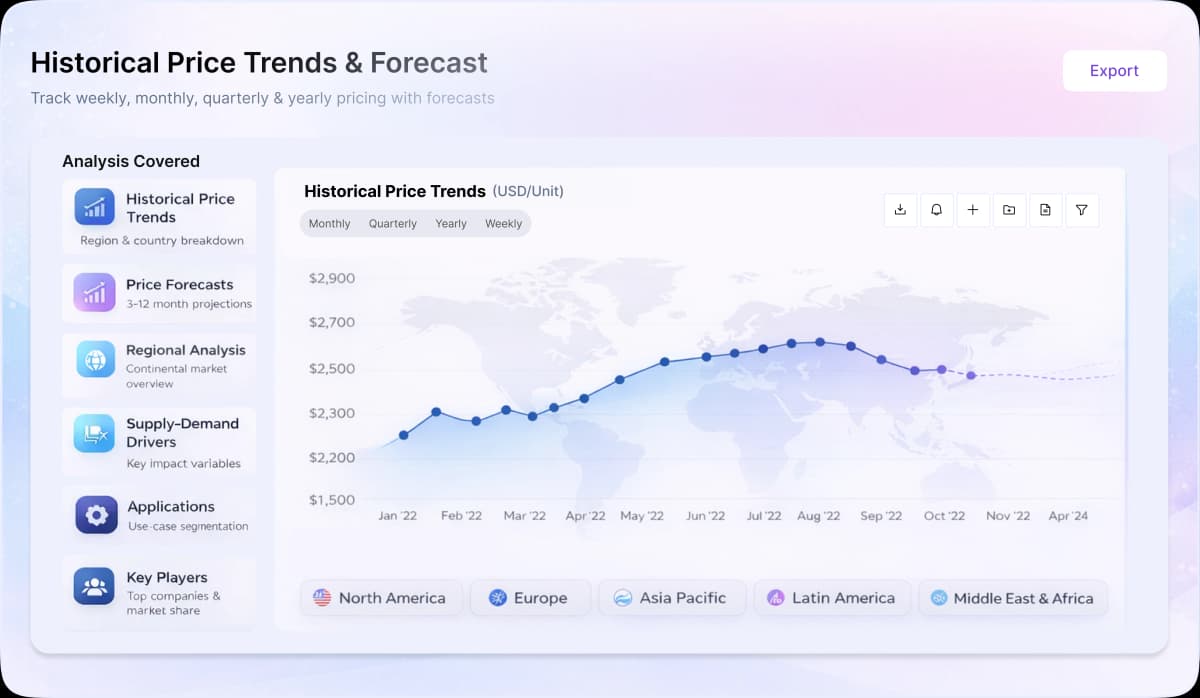
Refined soybean oil prices in China increased to ~USD 1,309.82/MT in April and ~USD 1,331.00/MT in June, showing a ~1.6% increase. In Russia, prices increased to ~USD 1,437.42/MT in April and ~USD 1,468.00/MT in June, showing a ~2.1% increase. Asian markets received early support from tighter soybean oil availability and lower inventories, which strengthened seller positions. However, conditions weakened later as soybean crushing increased and inventories rebuilt. The broader vegetable-oil supply outlook also limited gains, with Argentina’s 2025/26 sunflower seed production forecast at 7.0 million metric tons and sunflower oil exports projected at 1.8 million metric tons, according to the USDA Oilseeds report released in April. Increased competing oil availability reduced dependence on soybean oil and pressured price momentum. Global oilseed supply expectations also became more comfortable, with 2026/27 global oilseed production forecast at 718 million metric tons, according to the USDA Oilseeds report released in May. Overall, the refined soybean oil prices witnessed minimal fluctuations in the second quarter of 2026.