- Global sesame markets remained weak to stable during Q1’26 as elevated Chinese inventories and improving Indian supply outweighed localized supply concerns across exporting regions.
- Supply availability stayed comfortable due to rising sowing activity, ample carryover inventories, and aggressive export competition, while Strait of Hormuz disruptions slightly increased freight and logistics uncertainty.
- Demand from bakery, edible oil, tahini, confectionery, snack, and health-food industries remained steady but cautious, with buyers continuing hand-to-mouth procurement strategies.
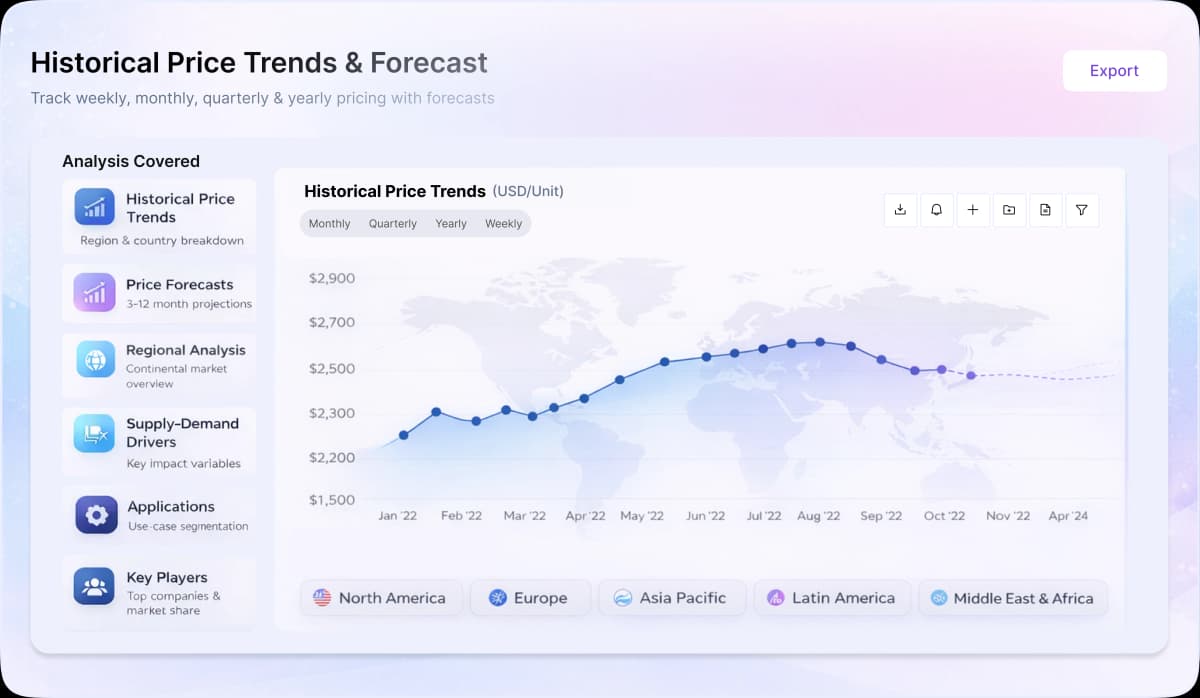
Sesame market sentiment remained subdued during Q1’26 due to abundant inventories and cautious downstream buying across major importing regions. In Asia, China continued dominating global trade activity, with Qingdao port sesame inventories rising to nearly 320,000 metric tons during February 2026 before easing later as processor procurement stayed slow amid sufficient supply availability. Indian market conditions remained comparatively balanced as summer sesame sowing increased nearly 20% year-on-year, reinforcing expectations of comfortable future supply. At the same time, weaker Chinese buying activity and elevated inventory levels limited stronger market recovery despite stable downstream consumption. Export competition also intensified as suppliers focused on clearing existing inventories amid soft international demand conditions. Downstream demand from edible oil manufacturing, tahini processing, bakery products, confectionery, and snack industries remained stable across Asia, Europe, and North America, although procurement largely stayed need-based due to cautious consumer sentiment.
Analyst Insight
According to Procurement Resource, sesame prices are expected to remain stable to weak as elevated inventories and improving crop availability continue outweighing moderate downstream demand recovery.