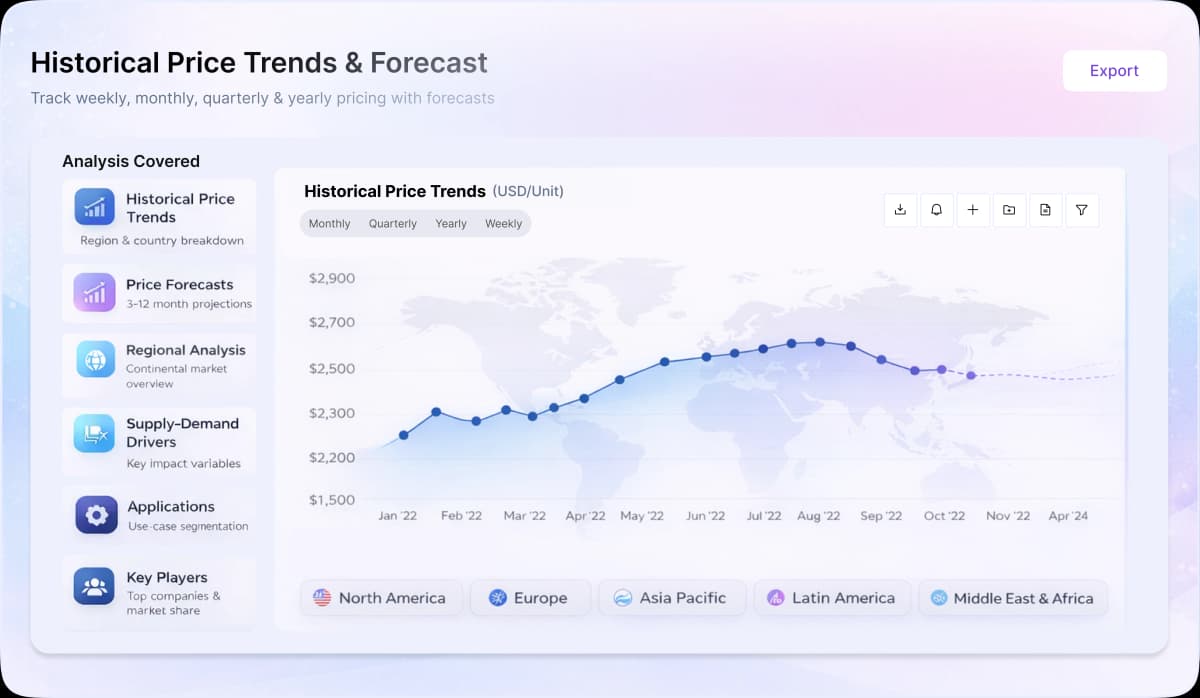
- Silicone (DMC) prices moved higher during H1’26 as supply adjustments, tighter trade conditions and rising raw-material and logistics costs gradually increased cost pressure.
- Feedstock and energy costs became more influential as the Middle East conflict disrupted oil, gas and chemical supply routes, while higher platinum costs added pressure earlier in the period.
- Downstream purchasing improved around electronics, new-energy and other applications, while logistics disruptions encouraged some buyers to secure material earlier.
Asia
In China, Silicone (DMC) prices averaged ~USD 2,167/MT in May and increased marginally to ~USD 2,175/MT in June. The H1 market shifted from relatively stable conditions early in the year toward firmer cost and supply conditions. Maintenance-related supply reductions and tighter logistics around the Lunar New Year supported buying activity, particularly as some downstream users replenished material ahead of expected requirements. During February and March, tighter production controls and changes to export policy further altered the supply balance. The removal of export tax rebates for primary polysiloxanes from April increased the cost implications for exporters and supported firmer market conditions. Later, Middle East-related disruptions raised chemical and logistics costs, adding further upward pressure. However, by the end of the quarter, the prices normalised as the logistical disruptions stabilised.
Europe
In Germany, Silicone (DMC) prices averaged ~USD 2,260/MT in May and rose by ~2% to ~USD 2,296/MT in June. Earlier in H1, higher platinum costs increased pressure on silicone production costs, particularly for addition-curing materials. Conditions became firmer in April as disruptions to Middle Eastern energy, raw-material supply and trade routes increased oil, gas and logistics costs. European supply also faced additional pressure from the planned closure of a major basic siloxanes facility in the UK, reducing regional availability. By late Q2, energy and logistics costs normalised, stabilising the manufacturing expenses.
North America
North American markets also faced higher production and logistics costs during H1’26. Global supply-chain disruptions increased regional raw-material and freight expenses, while the Middle East conflict added further pressure through energy and transportation channels. Additional increases in April reflected higher input and freight costs, keeping the cost environment firm despite comparatively stable broader market conditions. The combination of higher upstream expenses and trade-route uncertainty supported the gradual strengthening seen toward the end of H1.