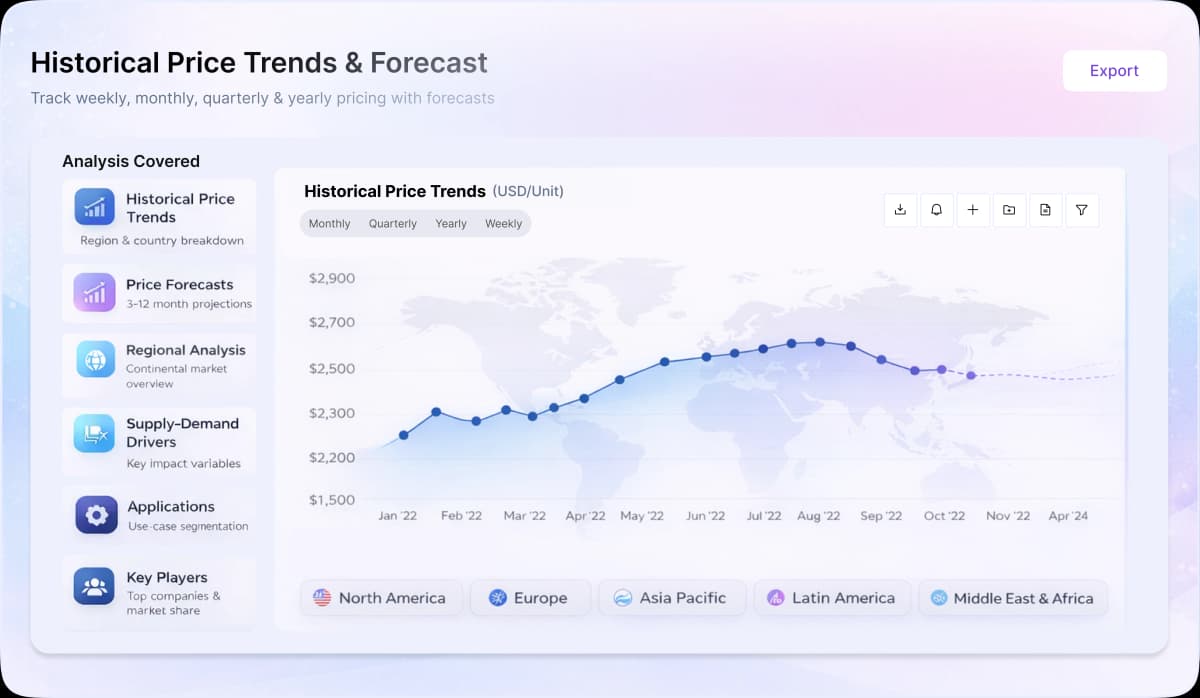
- Global coal prices stayed firm to volatile in Q1 2026, with supply-side disruptions and freight pressure supporting the market despite uneven industrial demand.
- Cost pressure rose as the Iran war disrupted energy routes and shipping, especially around the Strait of Hormuz, lifting freight, insurance, and replacement fuel costs.
- Downstream demand from coke producers and steel mills remained cautious, but restocking interest and energy-security concerns kept market sentiment supported.
Asia
In Asia, coal prices moved unevenly but ended higher in January 2026, the average price in China was 99.87 USD/MT, which increased to 104.19 USD/MT and 108.49 USD/MT in the subsequent months, respectively, up 8.63% over the period. Early-quarter support came from pre-holiday mine shutdown expectations and tighter near-term supply. After the Spring Festival, supply recovered faster than demand, which briefly pressured the market. By late March, the Iran war became the main driver.Disruptions to shipping and energy flows through the Strait of Hormuz raised freight costs and increased concern over fuel availability, which lifted coal sentiment across the region. Higher transport costs also made buyers more cautious and strengthened the cost floor for seaborne cargoes.
Europe
In Europe, the Iran war and the Strait of Hormuz disruption had a stronger effect than local industrial demand. The conflict tightened gas market sentiment, raised concern over LNG flows, and pushed utilities to reconsider coal as a backup fuel. Buyers in Northwest Europe turned more active in spot restocking as gas-to-coal switching improved coal competitiveness. The market was supported mainly by war-related freight escalation, higher gas prices, and the need to protect fuel security rather than by a clear recovery in end-use demand.
North America
In North America, coal prices remained relatively stable to firm, supported by stronger global seaborne sentiment. The Iran war and uncertainty around the Strait of Hormuz lifted international freight and energy costs, which tightened global pricing direction. Even without strong domestic demand acceleration, higher export-market risk and firmer seaborne values helped prevent downside pressure.