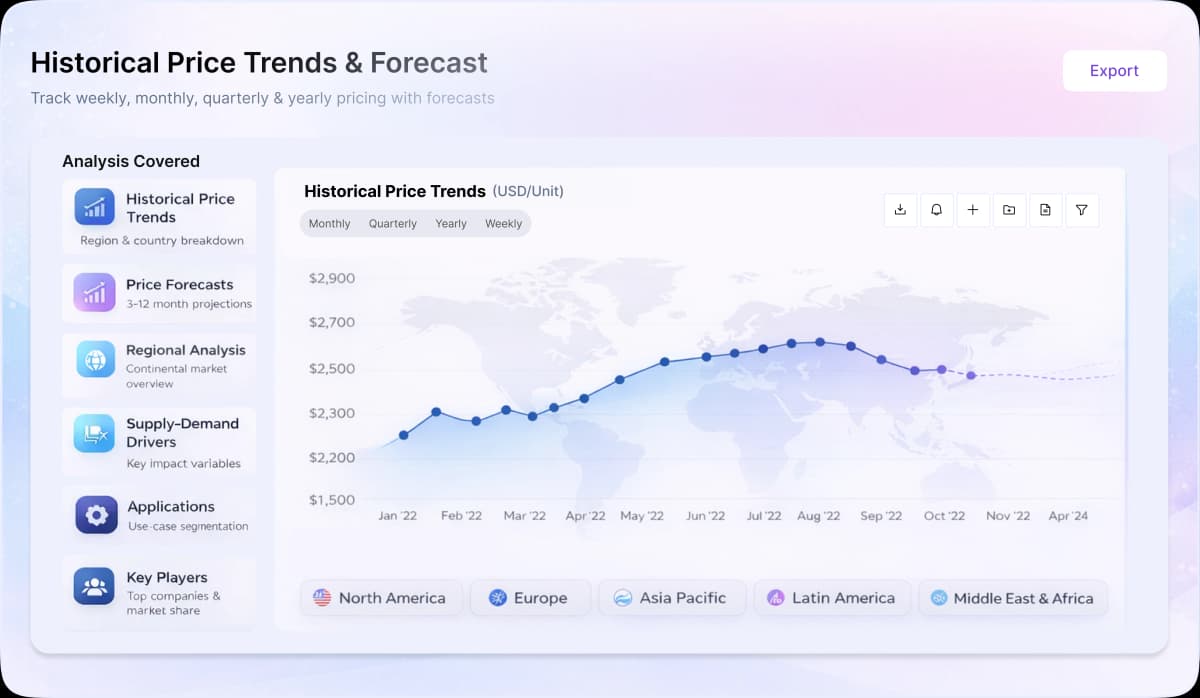
- Coffee prices declined in Q2’26 as Brazil’s larger crop outlook pressured Arabica, while Robusta remained firmer on tighter replacement supply.
- Feedstock pressure eased with better crop expectations, but fertilizer, freight, fuel, and low certified stocks kept delivered costs elevated.
- Downstream demand stayed resilient in retail and packaged coffee, though buyers resisted higher physical premiums and delayed aggressive restocking.
In Brazil, the prices of Coffee were ~BRL 34,231.54/kg and ~BRL 32,587.88/kg, respectively, showing a ~4.8% decrease in the first two months of Q2'26. The decline was mainly linked to an improved Brazilian crop outlook as production recovered strongly and Arabica availability improved. This reduced supply-risk premiums and encouraged sellers to accept lower price levels. In Guinea, the prices of Coffee were ~GNF 63,892,500.00/kg in April and ~GNF 60,882,270.00/kg in May, showing a ~4.7% decrease, following the same global downtrend. However, Robusta stayed relatively firm because Vietnam remained central to supply and certified stocks were low. Vietnam’s April exports reached a record April level, improving availability and reducing panic buying in Asia. Retail demand remained steady, especially in North America, where weekly coffee consumption stayed high, but roasters still faced freight disruptions.