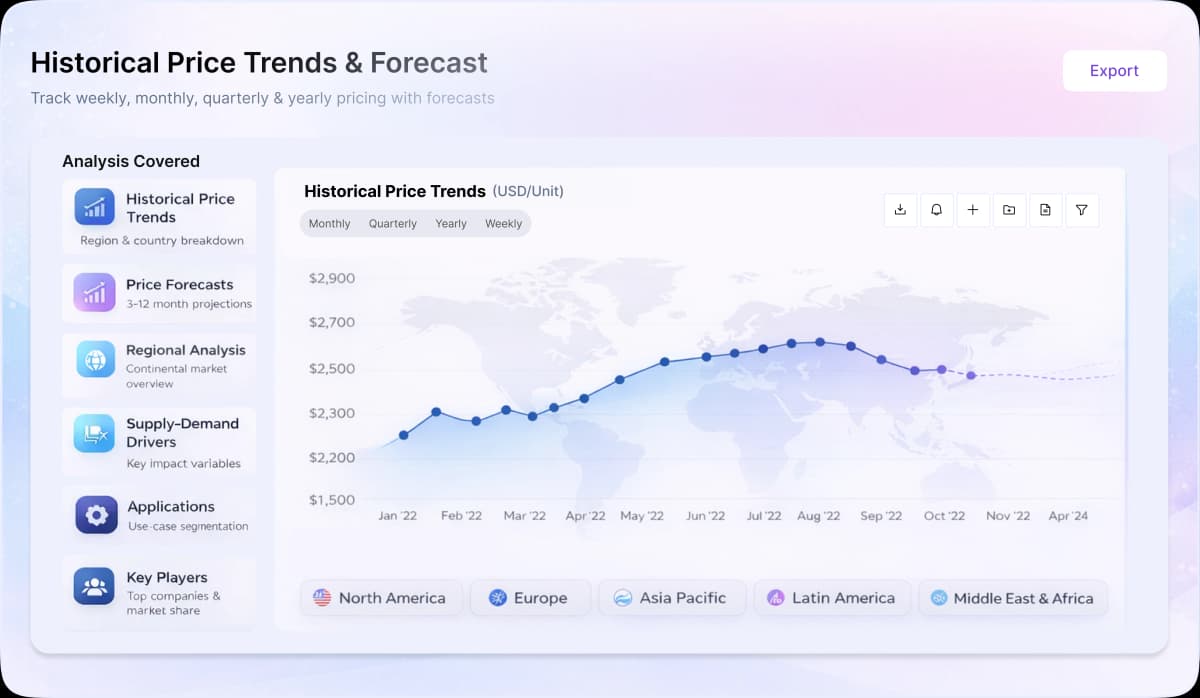
- Global silicon markets remained mixed during Q2’26, with modest firmness supported by trade protection and cost factors, while rising production and weak demand capped gains.
- Feedstock pressure stayed uneven as rainy-season hydropower lowered Chinese production costs, while trade barriers and operating economics supported firmer replacement costs elsewhere during Q2.
- Downstream demand remained cautious, although China’s silicon output remained high, as silicone and aluminium-alloy consumption failed to absorb rising supply.
Asia
In China, the prices of Silicon were ~USD 1,363.27/MT in April and ~USD 1,391.00/MT in June, showing a ~2.0% increase. Chinese conditions remained largely range-bound as a temporary May recovery was followed by renewed June pressure. Production reached about 331,300 MT in May, up 3.6% month on month and 7.6% year on year, while January-May output rose 6.0% to 1.632 million MT. Rainy-season hydropower encouraged furnace restarts in southwestern China, expanding availability and limiting stronger gains. The metal silicon market therefore remained under pressure from increased availability and cautious downstream buying. In India, the prices of Silicon were ~USD 1,413.27/MT in April and ~USD 1,479.00/MT in June, showing a ~4.7% increase. Firmer regional replacement costs and tighter imported supply supported the stronger increase.
Europe
European silicon conditions remained soft as subdued customer purchasing and competitive imported material pressured domestic producers. Entering Q2, a major producer’s global silicon-metal selling level had declined 6.9% from the previous quarter, reflecting weakness in Europe and the United States. Persistent low-priced imports constrained producers’ ability to sustain stronger market increases, keeping the regional metal silicon market subdued.
North America
In the United States, the prices of Silicon were ~USD 1,450.27/MT in April and ~USD 1,546.00/MT in June, showing a ~6.6% increase. Similarly, in Canada, the prices of Silicon increased from ~USD 1,453.27/MT and ~USD 1,551.00/MT during Q2'26. Meanwhile, U.S. trade protection supported regional firmness. Angola faced a 68.45% antidumping duty, Laos 94.44%, while Australia and Norway received dumping margins of 6.16% and 2.47%, respectively. Countervailing rates reached 32.57% for Australia and 17.27% for Norway, restricting lower-cost imports and supporting North American silicon values. These trade measures provided additional support to metal silicon prices across the region.
Analyst Insight
According to Procurement Resource, in the near term, silicon conditions are expected to remain firm in North America, while abundant Chinese production and competitive imports may keep Asian and European gains comparatively limited.